← All results

First Home Improvements

HOME IMPROVEMENTS · LEAD GENERATION · SOUTH OF ENGLAND

Replacing bought leads with a channel they own, in three months

Replacing bought leads with a channel they own, in three months

Replacing bought leads with a channel they own, in three months

First Home Improvements were buying leads from third parties: priced by someone else, shared with competitors, and leaving nothing behind. We built them a Google Ads channel of their own for the south region, tracked it through to closed deal value rather than to form fills, and had it competing with national brands inside a quarter.

First Home Improvements were buying leads from third parties: priced by someone else, shared with competitors, and leaving nothing behind. We built them a Google Ads channel of their own for the south region, tracked it through to closed deal value rather than to form fills, and had it competing with national brands inside a quarter.

SERVICES WE RUN

PPC

CRO

MARKETING SOLUTIONS

Lead Generation

D2C Marketing

Performance Marketing

Profitability Growth

◆ AT A GLANCE ◆

The short version

The short version

The short version

Four figures that describe the result without describing the business. Every number on this page is a share, a rate or a movement.

Four figures that describe the result without describing the business. Every number on this page is a share, a rate or a movement.

3 months

3 months

To a profitable channel they own

Built from zero, against national brands with years in the same auctions.

63%

63%

Close rate on appointments sat

Of every appointment the team attended, nearly two in three closed.

~9 in 10

~9 in 10

Closed deal value from non-brand activity

The advertising is creating demand, not harvesting it.

−43%

−43%

Cost per lead, month three vs month one

Same channel, same market, three months of compounding.

At the client’s request, every figure on this page is a share, a rate or a relative movement. We have not published ad spend, lead volumes, cost per lead, deal values or return on spend in absolute terms, and no two figures here can be combined to derive any of them. If you want the absolute numbers, the client is happy for us to walk through them on a call under NDA.

◆ THE STARTING POINT ◆

Where they started

Where they started

Where they started

Buying leads is not a marketing channel. It is a supplier relationship.

Buying leads is not a marketing channel. It is a supplier relationship.

First Home Improvements sell and install windows, doors and conservatories. Like most companies in the category, a large share of their enquiries came from pay-per-lead providers: you pay a fixed price per contact, the same contact is usually sold to two or three of your competitors at the same time, and when you stop paying, you have nothing.

First Home Improvements sell and install windows, doors and conservatories. Like most companies in the category, a large share of their enquiries came from pay-per-lead providers: you pay a fixed price per contact, the same contact is usually sold to two or three of your competitors at the same time, and when you stop paying, you have nothing.

That is the real problem with bought leads. The price is set by somebody else, the quality is whatever arrives, and four years of buying them leaves you exactly where you started. There is no account, no data, no landing pages and no asset. This was lead generation in the strict sense, and the brief was to build something they would own outright.

That is the real problem with bought leads. The price is set by somebody else, the quality is whatever arrives, and four years of buying them leaves you exactly where you started. There is no account, no data, no landing pages and no asset. This was lead generation in the strict sense, and the brief was to build something they would own outright.

The target was explicit: a channel that produced enquiries more cost-efficiently than the pay-per-lead sources, in the south region, competing in the same search auctions as national brands with established budgets and years of history. Profitability growth, not volume — the measure was the cost of a closed deal, not the cost of a contact.

The target was explicit: a channel that produced enquiries more cost-efficiently than the pay-per-lead sources, in the south region, competing in the same search auctions as national brands with established budgets and years of history. Profitability growth, not volume — the measure was the cost of a closed deal, not the cost of a contact.

WHAT WE INHERITED

No Google Ads account, no conversion tracking and no landing pages of their own

A category where three national brands hold the majority of available search impressions

A sales process where most enquiries arrive by phone, so form tracking alone would have measured almost nothing

A lead definition inherited from pay-per-lead suppliers, where any contact counts as a lead regardless of whether it is a sales enquiry at all
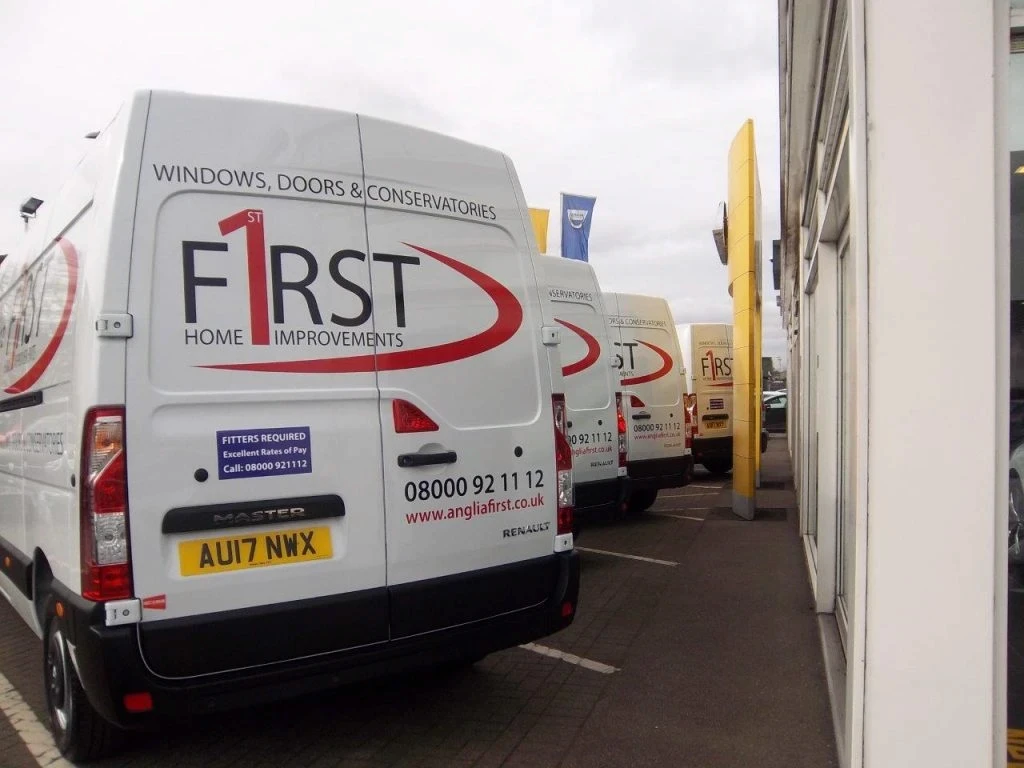
First Home Improvements fleet

◆ THE DIAGNOSIS ◆

What the build had to get right

What the build had to get right

What the build had to get right

Four things decided whether this beat the pay-per-lead sources or just matched them at a different price.

Four things decided whether this beat the pay-per-lead sources or just matched them at a different price.

Most contacts are not sales enquiries, and counting them lies

Most contacts are not sales enquiries, and counting them lies

Roughly seven in ten of the contacts coming through any channel in this category are service calls, wrong-company calls, duplicates or rows with no usable contact details. Those are stripped out before anything is claimed, so the number reported is genuine enquiries rather than raw volume. Judge a pay-per-lead supplier on the same basis and the comparison changes completely.

The offer had to be built before the ads were

The offer had to be built before the ads were

Strategic planning of what was actually being offered on each product line came first: the proposition, how it was priced against the national brands, and what would make someone choose a regional installer. Paid search cannot sell an offer that does not stand up next to the competition.

The landing page decides whether the click becomes an enquiry

The landing page decides whether the click becomes an enquiry

Landing pages were built per product line and improved continuously rather than once, with the objection that stops a homeowner answered on the page. In a category where a click costs what it costs here, conversion rate on the page is the single biggest lever on cost per deal.

Measure to closed revenue, not to conversions

Measure to closed revenue, not to conversions

Every lead is tracked through to genuine enquiry, to appointment sat, to closed deal and to its value, with phone orders verified keyword by keyword against the call details. It is the only way to know whether a channel beat a pay-per-lead supplier, and it is what proved that roughly nine in ten of closed value came from non-brand activity.

◆ THE WORK ◆

How it was built, in order

How it was built, in order

How it was built, in order

One quarter, built from nothing, against established national competition.

One quarter, built from nothing, against established national competition.

PHASE 01

Weeks 1–2

Offer and proposition first

Offer and proposition first

Before any spend, strategic planning of what was being offered on each product line and how it would be positioned against the national brands already dominating the auctions. The ads were written to that proposition rather than the proposition being retrofitted to the ads.

CRO

PHASE 02

Weeks 2–4

Account built from zero

Account built from zero

Campaigns, conversion tracking and call tracking built from nothing. Search took the high-intent demand, Performance Max extended reach, and roughly nineteen in twenty of media spend went to Google Ads with a small Meta retargeting layer behind it to catch the people who had already visited.

PPC

PHASE 03

Ongoing

Landing pages built and then improved

Landing pages built and then improved

Pages built per product line rather than shared, then changed continuously through the period on what the data showed. Conversion work was treated as a standing job, not a project with an end date — which is why cost per lead fell by more than forty per cent between the first month and the third.

CRO

PPC

PHASE 04

Ongoing

Tracked through to the closed deal

Tracked through to the closed deal

Leads followed through four stages: contact, genuine sales enquiry, appointment sat, closed order with a value. Phone orders verified against the call details report, keyword by keyword. The reporting the client gets is a lead-to-deal report, not a conversions dashboard.

PPC

PHASE 05

Month 3

Competing with the national brands

Competing with the national brands

By the end of the first quarter the account was appearing in the single top advertising position roughly twice as often as two of the national brands in the same auctions, on a fraction of their impression share. Position, not budget, is how a regional installer wins against a national one.

PPC

A First Home Improvements conservatory

◆ HOW IT IS RUN ◆

How the account is run

How the account is run

How the account is run

The operating model matters as much as the work. This is what the client deals with week to week.

The operating model matters as much as the work. This is what the client deals with week to week.

One principal operator

The person who built the account is the person who runs it and the person on the call. No account manager relaying instructions, and no junior learning on the budget.

Every call reviewed, not sampled

Calls are listened to and classified rather than counted. A thirty-three second call that Google’s own reporting discounted turned into one of the largest orders of the period — automated conversion counting would have thrown it away.

Weekly, not monthly

Search terms, landing page performance and lead quality reviewed every week. On a new account in a competitive auction, a month of drift is a month of budget.

Judged on closed deals

The report the client is given runs from contact to closed order value. A cost per lead that looks good and produces nothing is a worse outcome than a higher one that fills the diary.

Reallocation is built in

Effort moves to whichever part is the constraint. Across this build that meant the offer first, then the landing pages, then the bidding.

Everything is theirs

Account, tracking, landing pages and data sit in the client’s name and have from day one, on thirty days’ notice. That is the entire point of building it rather than buying leads.

◆ WHAT MOVED ◆

What the first quarter looked like

What the first quarter looked like

What the first quarter looked like

Shares, rates and movements only. No absolute spend, lead volumes, deal values or returns.

Shares, rates and movements only. No absolute spend, lead volumes, deal values or returns.

Cost per lead, month three vs month one

Cost per lead, month three vs month one

−43%

−43%

Same channel, same market

Same channel, same market

Close rate on appointments sat

Close rate on appointments sat

63%

63%

Nearly two in three attended appointments closed

Nearly two in three attended appointments closed

Share of closed deal value from non-brand activity

Share of closed deal value from non-brand activity

~9 in 10

~9 in 10

Creating demand rather than harvesting it

Creating demand rather than harvesting it

Share of contacts that were genuine sales enquiries

Share of contacts that were genuine sales enquiries

~3 in 10

~3 in 10

The rest stripped out before anything is claimed

The rest stripped out before anything is claimed

Converting journeys with more than one ad click

Converting journeys with more than one ad click

29%

29%

Buyers in this category do not convert on first click

Buyers in this category do not convert on first click

Performance Max assisted conversions vs its own last-click count

Performance Max assisted conversions vs its own last-click count

77%

77%

It creates demand that closes elsewhere

It creates demand that closes elsewhere

Top-of-page position rate vs two national competitors

Top-of-page position rate vs two national competitors

~2x

~2x

On a fraction of their impression share

On a fraction of their impression share

Share of available search impressions captured

Share of available search impressions captured

~1 in 9

~1 in 9

The headroom still in front of the account

The headroom still in front of the account

Funnel rates are measured from contact through to closed order over the first four months of the account. Movements compare the first month to the third. Competitive position is from Google’s own auction insights. We have not published ad spend, lead volumes, cost per lead, deal values or return on spend in absolute terms, and no figure here can be combined with another to derive one.

Funnel rates are measured from contact through to closed order over the first four months of the account. Movements compare the first month to the third. Competitive position is from Google’s own auction insights. We have not published ad spend, lead volumes, cost per lead, deal values or return on spend in absolute terms, and no figure here can be combined with another to derive one.

“A bought lead is priced by somebody else, sold to your competitors at the same time, and gone the moment you stop paying for it. The point was to own the channel instead.”

“A bought lead is priced by somebody else, sold to your competitors at the same time, and gone the moment you stop paying for it. The point was to own the channel instead.”

Principal operator, TGMA

◆ WHAT IS NEXT ◆

What we are working on now

What we are working on now

What we are working on now

A case study is a snapshot of an account that is still running. These are the current priorities.

A case study is a snapshot of an account that is still running. These are the current priorities.

Recovering the cancelled and unattended appointments, which are genuine enquiries already paid for and the cheapest revenue available to the account

Taking impression share up from roughly one in nine, where the national brands still hold the majority of the auctions

Extending the same build into the remaining product lines on the back of the proposition work already done

Keeping brand and non-brand activity in one account, because separating them would cut more than a third of the conversion evidence the bidding runs on

Still buying leads from somebody else?

Still buying leads from somebody else?

Still buying leads from somebody else?

Before anything else we produce a full strategy for your business, free. Where the opportunity is, what we would build, in what order, what it would cost and what we forecast it to return. Yours to keep whether or not you work with us.

Before anything else we produce a full strategy for your business, free. Where the opportunity is, what we would build, in what order, what it would cost and what we forecast it to return. Yours to keep whether or not you work with us.